10:39 am
October 16, 2026
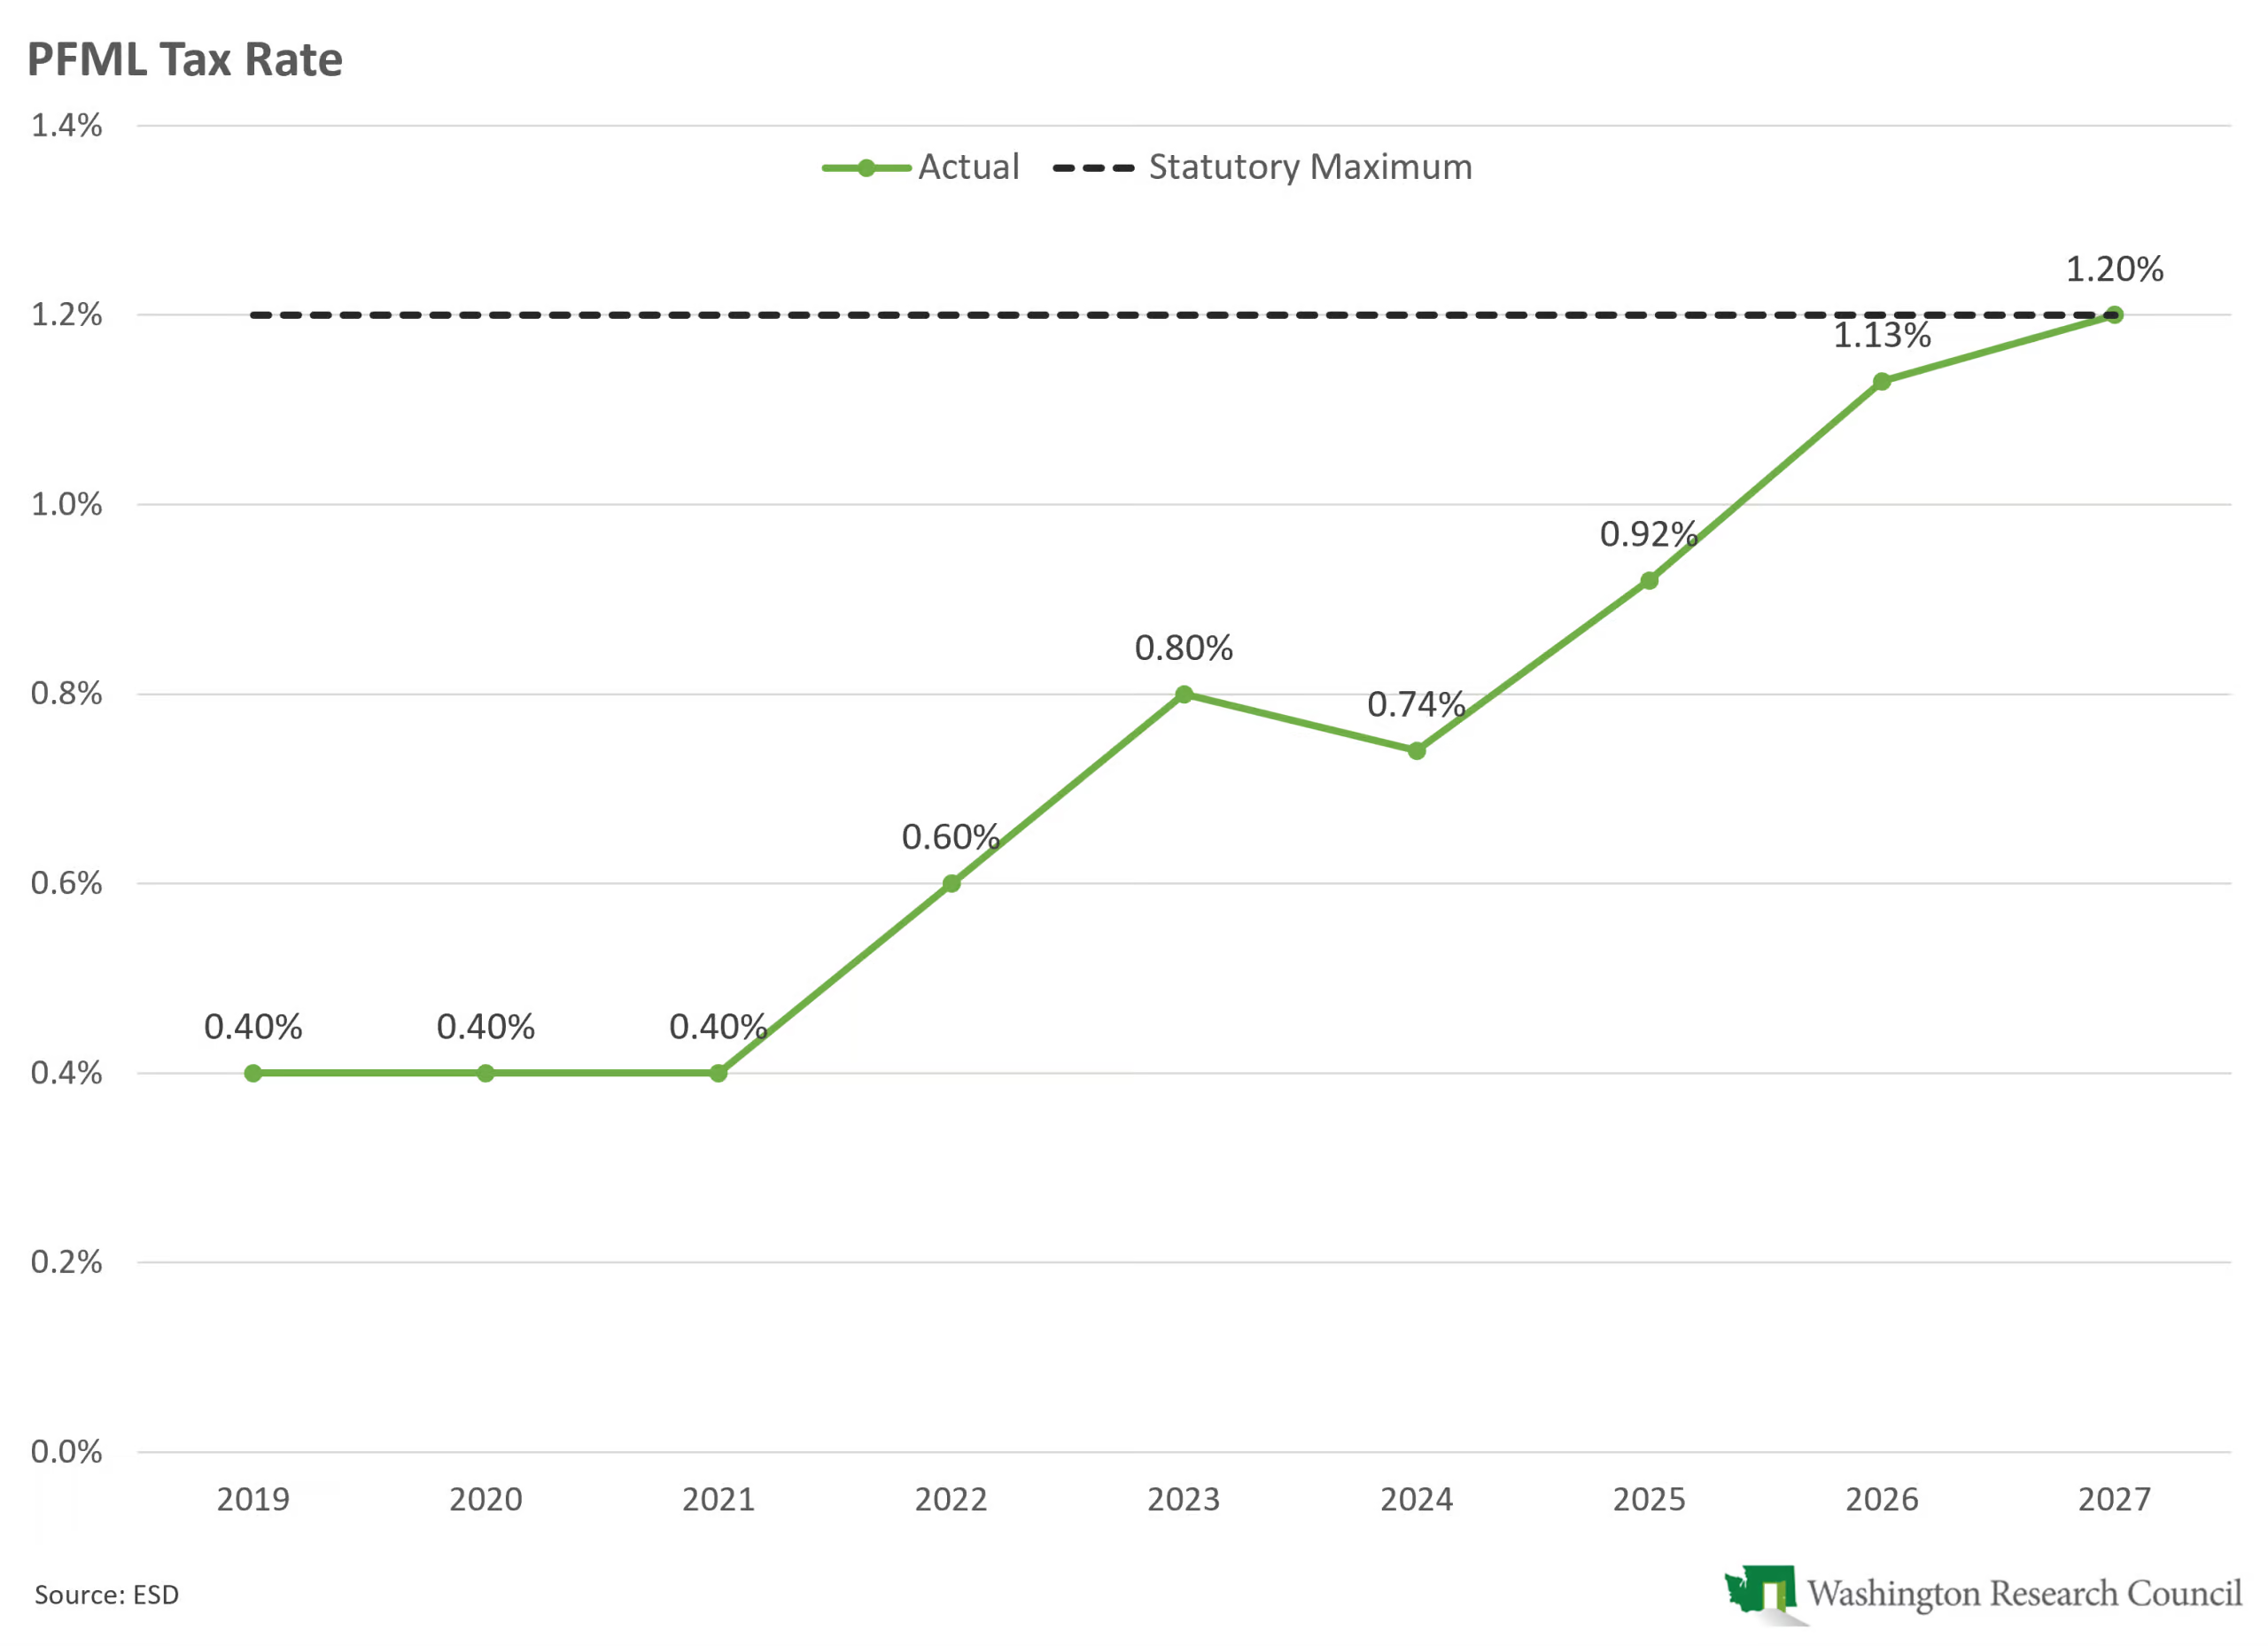
The paid family and medical leave (PFML) tax rate will increase from 1.13% to 1.2% beginning Jan. 1, 2027. By statute, responsibility for the premiums is split between employers and employees. In 2026, employers are statutorily responsible for 28.57% of the premium; in 2027, they will be responsible for 29.3%. (Employers may choose to cover the employee portion rather than withholding it from wages.)
The PFML tax is paid on wages up to the Social Security maximum. In 2026, that is $184,500. In 2027, it will be $192,300. As I wrote in June, PFML maximum weekly benefits are also increasing in 2027.
The tax rate for the next calendar year is currently calculated by taking 140% of the prior fiscal year’s expenses less the balance of the family and medical leave insurance account on Sept. 30 of the current year, and then dividing by the prior fiscal year’s taxable wages. Beginning in 2028 (for CY 2029 tax rates), the tax rate will be based on an actuary’s annual report on the program’s experience and financial condition.
The statutory maximum tax rate is 1.2%. It’s not clear if the 1.2% rate for CY 2027 was indicated by the calculation, or if the indicated rate was higher and constrained by the statutory cap. Regardless, the Employment Security Department (ESD) has estimated that the PFML program will experience sustained deficits beginning in 2029. During a House Labor & Workplace Standards work session last week, ESD said, “Short-term deficit cycles persist due to benefit expenses outgrowing premium revenue.”
The next annual actuarial report is due to the Legislature by Nov. 1. An additional report that was required by the 2026 supplemental budget is also due Nov. 1. It must evaluate the solvency of the PFML program and include “potential program changes to achieve long-term fund solvency.”